Digital Money in Banking: Tokenized Deposits or Stablecoins
Banco Santander, Bank Frick, Iberpay and TaxBit discuss at MERGE Madrid 2026 when to use tokenized deposits or stablecoins: programmable payments, issuer risk, 24/7 service, interoperability, tax reporting and AI agents
30min · Full recording from 28/10/2026 at MERGE Stage. Also available on YouTube.
Digital money in banking: tokenized deposits or stablecoins
Overview
Tokenized deposit or stablecoin? In this MERGE Madrid 2026 panel, moderated by Banco Santander, its corporate and investment bank, Bank Frick, Iberpay and TaxBit compare the private forms of digital money and when each one fits. They explain what tokenization adds to a European payment system that is already instant, how risk changes with the instrument, what clients are asking for, how to stop every bank from building its own island and which compliance and reporting obligations come with these assets.
What you'll learn
- Smarter payments: why the opportunity is programmability rather than speed
- Tokenized deposit or stablecoin: banking relationship, reach and risk of each instrument
- 24/7 demand: what institutional clients now ask a bank for
- Fragmentation and interoperability: how to connect the different forms of money
- Threat or opportunity: the effect of stablecoins on bank deposits
- Compliance and tax reporting: the obligations that come with digital money
Session summary
Smarter payments, not faster ones: Iberpay, which runs Spain's interbank payment infrastructure, points out that Europe already moves money between accounts in under a second. In its view, tokenization is not there to fix speed but to enable programmable payments, which it distinguishes from programmable money, a more controversial idea. It expects a hybrid ecosystem, with several forms of money and several ledgers, that has to work alongside today's infrastructure without reinventing it.
How to choose between deposit and stablecoin: Banco Santander's corporate and investment bank says it asked its clients about their preference: some do not know the difference, some have a clear preference and others do not mind. That is why it believes a bank should be able to offer both. A tokenized deposit extends the banking relationship, since it is a digital liability on the bank's balance sheet, but it stays within the bank's perimeter. A stablecoin fits better when the goal is reach and portability on public networks. In one case the risk is the bank's and in the other the issuer's. In the end, it argues, clients ask for a service, not a product.
What clients are asking for: Bank Frick, a Liechtenstein private bank that has worked with digital assets for ten years, explains that its core business is on and off ramping between traditional money and digital assets for financial institutions. Its clients already move traditional money among themselves at any hour within the bank's network and now want the same for digital assets, along with tokenized products they can buy at the weekend. According to the bank, delivering that for real requires stablecoins or another means of payment available out of hours and infrastructure that is ready for it. It is not part of any consortium and prefers to partner with technology providers.
Fragmentation and interoperability: if every bank issues its own tokenized deposit, money could fragment. Banco Santander replies that this is not a tokenization problem but stems from the nature of a deposit, which has always needed a clearing system behind it. The challenge is to avoid highly efficient digital islands that do not talk to each other, and that calls for a framework of governance, standards and legal and compliance rules more than for technology. As ways forward it cites Pontes, the Eurosystem initiative to settle in central bank money, the Agorá project of the Bank for International Settlements and the industry's work on new ledgers. Iberpay agrees that wholesale central bank money should act as the anchor.
Threat or opportunity: for Bank Frick, stablecoins can be a threat to deposits, but for a bank that knows how to handle them they are above all an opportunity. The business does not change: the bank still has to place balances to earn a return. What changes is the type of asset, which works around the clock, faster and at lower cost. Whether it is safer depends on who issues it.
Compliance and tax reporting: TaxBit argues that compliance is what has allowed crypto platforms to offer traditional financial products and banks to offer crypto assets. On top of identity checks, anti-money laundering controls and transaction monitoring come tax reporting obligations, such as the new version of the Common Reporting Standard (CRS 2.0), the Crypto-Asset Reporting Framework (CARF) and the European directive DAC8, which according to the company also reach stablecoins and tokenized deposits.
What to expect in the coming years: Iberpay expects different forms of money split by use case and payments that are invisible to the user, partly carried out by AI agents. Bank Frick expects tokenized assets to gain share against traditional ones. Banco Santander anticipates that almost every bank will be connected through interoperable tokenized deposits, with broad use of stablecoins, including by AI agents. TaxBit believes managing assets and payments will become as seamless as paying with a phone is today.
Watch the full talk
Watch the full recording of the panel on MERGE's YouTube channel, with Banco Santander, Bank Frick, Iberpay and TaxBit on tokenized deposits, stablecoins and the future of digital money.
FAQs
How does a tokenized deposit differ from a stablecoin?
According to Banco Santander, a tokenized deposit is a digital liability on the bank's balance sheet and extends the banking relationship. A stablecoin circulates on public networks with wider reach and its risk is that of its issuer.
Is digital money needed if European payments are already instant?
According to Iberpay, the opportunity lies not in speed but in making payments programmable and connecting the new forms of money with today's infrastructure.
Are stablecoins a threat to bank deposits?
According to Bank Frick, they can be, but for banks that know how to handle them they are above all an opportunity, because the underlying business does not change.
How do you stop every bank from building its own island?
According to Banco Santander, with a common framework of governance, standards and rules, and with central bank money as the settlement asset between institutions.
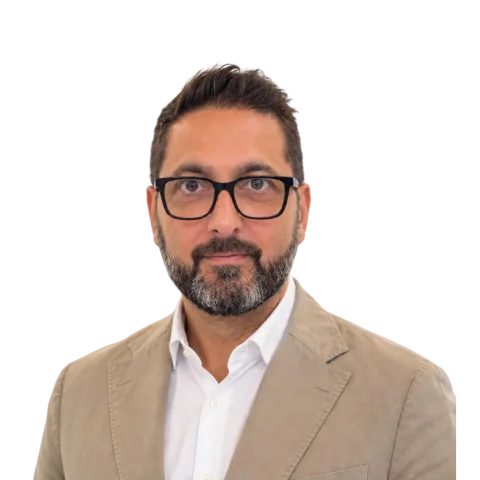
Juan Jimenez Zaballos
Global Head of Digital Banking Public Policy at Banco Santander



