Stablecoin Geopolitics: Dollar, Euro and Monetary Sovereignty
The Global Blockchain Business Council, Yellow Card, Fireblocks and StablR discuss at MERGE Madrid 2026 the geopolitics of stablecoins: why almost all are dollar pegged, what the euro needs to compete, the role of Visa, Mastercard and Swift and what Europe can learn from emerging markets
30min · Full recording from 29/10/2026 at MERGE Stage. Also available on YouTube.
Stablecoin geopolitics: dollar, euro and monetary sovereignty
Overview
If money moves to the internet, in which currency and who controls it? In this MERGE Madrid 2026 panel, moderated by the Global Blockchain Business Council and with Yellow Card, Fireblocks and StablR, the geopolitics of stablecoins is discussed. The starting point is that almost all supply is pegged to the dollar, and from there the panel debates whether that accelerates dollarization, what the euro would need to compete and what role the big payment players play.
What you'll learn
- Dollar dominance: why almost all stablecoins are dollar pegged and what it implies
- Dollarization: whether stablecoins accelerate it or just make existing demand more efficient
- The euro challenge: regulation, distribution and liquidity to gain relevance
- Big players: Visa, Mastercard and Swift moving into tokenized money
- Emerging markets: what Europe can learn from already dollarized economies
- What will settle: stablecoins, tokenized deposits or central bank money
Session summary
The starting point: the moderator recalls that the vast majority of stablecoins are pegged to the dollar, and asks whether that accelerates the dollarization of the on-chain economy. From the infrastructure side the answer is that, more than dollarization, what speeds up is the efficiency and speed of movements, and that the sector's big challenge is to provide trust, controls and security so people feel comfortable using these assets.
Demand that already existed: from Yellow Card, focused on emerging markets, it is stressed that demand for dollars has existed for decades in dollarized economies; what is new is that stablecoins settle in seconds and at low cost payments to suppliers or transfers that took days through traditional rails. The geopolitical dilemma appears when a company or a person decides to keep their savings in a dollar stablecoin instead of their local currency, and when the reserves of those stablecoins reinforce demand for US government debt.
Dollar influence: it is explained that the US economy relies on a strong dollar and on the world buying its debt, and that, although that hegemony had been declining, stablecoins have reversed the trend: today the dollar is almost the entirety of the new on-chain economy. Holding dollars in a stablecoin is, according to the panel, like holding dollars without a US bank branch.
The big payment players: the panel notes that Visa, Mastercard and Swift are integrating stablecoins and tokenized money, with stablecoin settlements growing strongly. The brake on full adoption, it is pointed out, is not so much the technology as the merchants, who do not yet accept stablecoins widely, and the fact that Swift is working to bring its messaging onto these rails in a compatible and compliant way.
The euro challenge: from StablR it is argued that the euro needs a regulatory shift. In its view, MiCA has brought clarity but has made things hard for euro stablecoins, partly because the regulator would prefer a public digital euro; the argument is that stablecoins are the best way to export the euro and give it global relevance, and that today its weight versus the dollar is minimal. Other voices add that regulation is necessary but not sufficient: a commercially viable and scalable framework is needed, with real demand, liquidity and efficiency.
Sovereignty and emerging markets: with examples from Latin America, Africa and Asia, the panel asks what Europe can learn from economies that have lived with dollarization for decades: trust in the currency, competitive infrastructure and accessibility matter as much as economic strength. It also addresses what comes with artificial intelligence agents that are starting to pay for services in stablecoins, where the consensus is that limits and controls will be needed before giving them free access to a wallet.
What will settle: asked whether Europe needs a dollar stablecoin, a digital euro or both, and what banks will use as they move on chain, the infrastructure side observes that the conversation revolves mostly around stablecoins and tokenized deposits, with very little real interest in central bank digital money. In the closing scenarios, the panel leans mostly towards a future of several currencies coexisting, though with the dollar keeping its predominance.
Watch the full talk
Watch the full panel on MERGE's YouTube channel, with the Global Blockchain Business Council, Yellow Card, Fireblocks and StablR on the geopolitics of stablecoins and the contest between the dollar and the euro.
FAQs
Why are almost all stablecoins dollar pegged?
Because the dollar is omnipresent and easy to use as an on and off ramp, and because their reserves reinforce demand for US debt, which consolidates its predominance in the on-chain economy.
Do stablecoins accelerate dollarization?
According to the panel, rather than creating it, they make much more efficient a demand for dollars that already existed for decades in emerging markets.
What does the euro need to compete?
A regulatory framework that does not penalize euro stablecoins and, in addition, distribution, liquidity and a commercially viable and scalable model.
What will banks settle in as they move on chain?
The panel sees more interest in stablecoins and tokenized deposits than in central bank digital money.
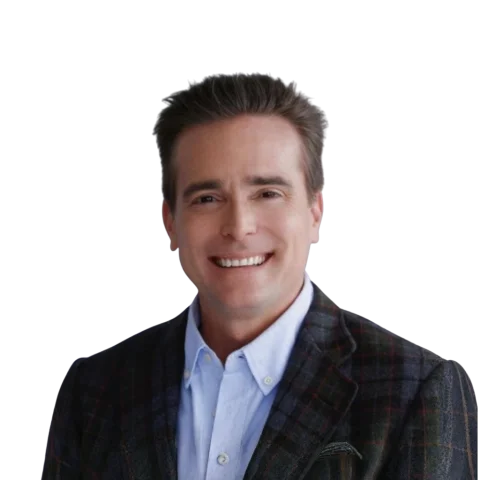
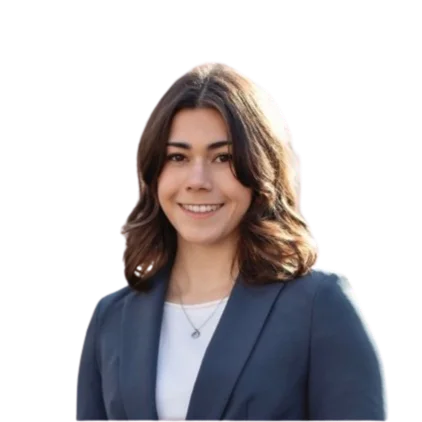
Alfredo Oballos Diaz
Chief of Staff, EMEA (Europe, Middle East, and Africa) at Global Blockchain Business Council (GBBC)



